The jurisdiction is not chosen for the ease of issuing the token. It is chosen for the fund regime, for access to investors, and for something almost nobody compares: where the investors’ rights will actually be enforceable.
Anyone setting out to establish a tokenised fund tends to begin by comparing jurisdictions, and tends to begin with the wrong question: where is it easiest to issue units on a blockchain?
That question arrives too late, for the reason examined in the previous article: a tokenised fund is still a fund. The technology used to represent its units removes no obligation of authorisation, management, depositary, disclosure or investor protection, and confers no freedom to market those units anywhere.
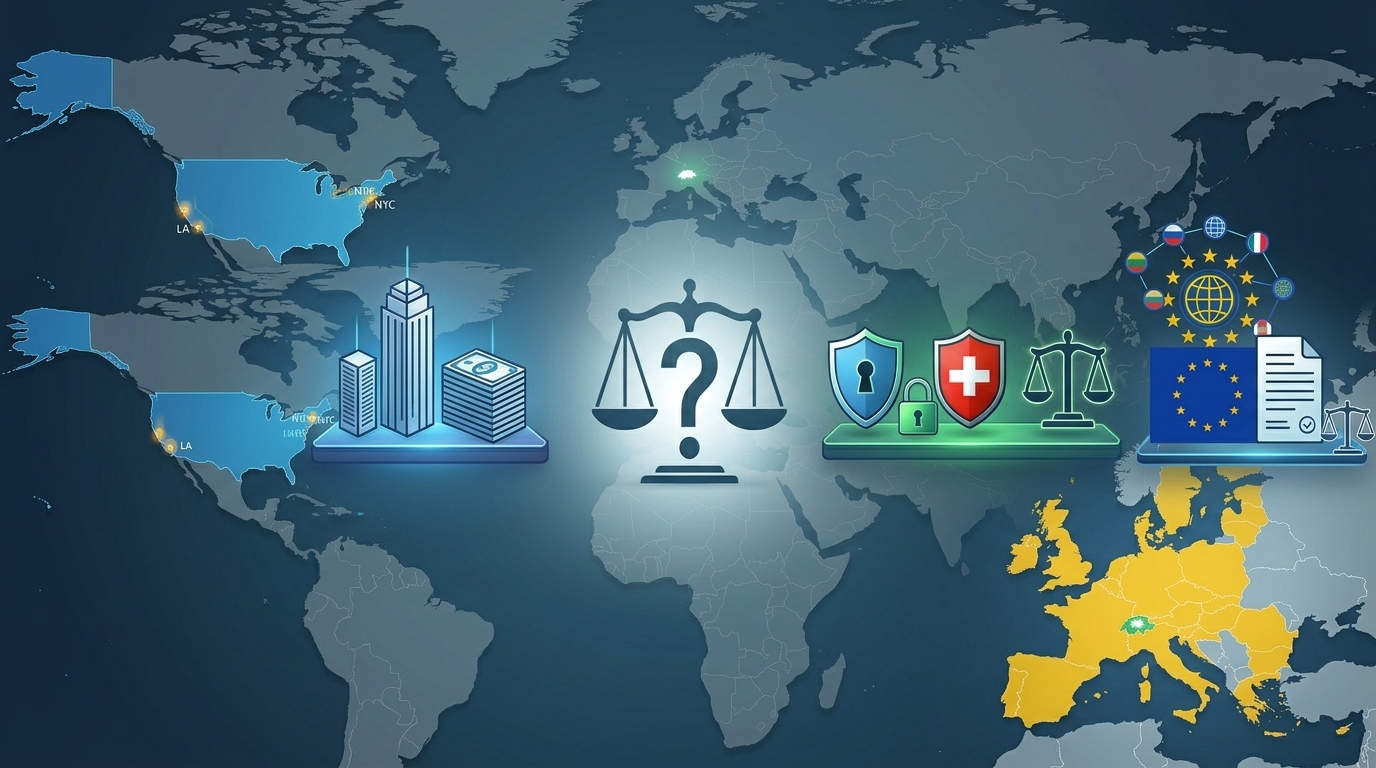
Choosing a jurisdiction therefore requires separating three questions that are routinely conflated: where the fund is established, where its investors are, and which law recognises and protects title to what has been tokenised. And then there is a fourth, which is ours, and which no comparison table tends to include.
1. The United States: the market, under securities law
The American attraction is access: market depth, institutional investors and financial infrastructure, particularly in money market funds and government debt.
What it does not offer is an exit from securities regulation. Representation on a blockchain does not of itself alter the legal nature of the instrument, and the fund’s structure determines the applicable rules: a registered fund falls under the Investment Company Act of 1940 as to valuation, liquidity, custody and redemption, and the issuance and distribution of its units under federal securities law. Private structures may rely on exclusions from the investment company regime and on exemptions from offering registration, but the two should not be conflated: an exemption from registering the offering does not exclude the rules applicable to the fund itself.
That the technology fits within that framework is already demonstrated. The JPMorgan OnChain Liquidity-Token Money Market Fund, for which documentation was filed with the SEC in 2026, provides an example of integrating tokenised units into a US money market fund structure. It is not an exception to the system; it is the system admitting a different way of representing the same thing.
When it suits. Where the project addresses the US market, seeks US institutional investors, or needs to sit within that infrastructure. Its difficulty is the cost of compliance. And establishing the fund outside the United States does not remove the restrictions on marketing it to US investors.
2. Switzerland: legal certainty and the qualified investor route
Switzerland combines a developed legal system, a tradition in wealth management, and a framework that recognises certain forms of digital representation of rights. That framework assists the recognition of DLT-based instruments, but it does not turn any token into valid title, nor does it displace collective investment scheme law.
Two concrete reference points order the picture.
The first: FINMA approved the Crypto Market Index Fund on 29 September 2021, the first Swiss-law fund investing principally in crypto-assets, categorised as an “other fund for alternative investments” and restricted to qualified investors. The approval came with express conditions — investment limited to established crypto-assets with sufficient trading volume; dealings through counterparties and platforms based in FATF member countries and subject to anti-money-laundering rules; and specific risk management and reporting requirements on the institutions involved in management and custody. Traditional structures admitting exposure to digital assets, in other words, rather than a separate regime.
The second: the Limited Qualified Investor Fund (L-QIF), in force since 1 March 2024. It requires neither individual FINMA authorisation nor approval and is not subject to direct FINMA supervision as a product. But the rest is worth reading: it may be offered solely to qualified investors; it must be managed by FINMA-supervised institutions, on whom compliance with the L-QIF rules themselves also falls; it must be identified as an L-QIF on the front page of the fund documents and in advertising; investors must be expressly informed that the vehicle is exempt from authorisation, approval and supervision; and the Federal Department of Finance maintains a public register of all of them.
The L-QIF is therefore not an unregulated fund: it is a fund whose regulatory control has moved from the product to whoever manages it. And the fact that one may be established does not of itself authorise any model of tokenising its units: the form of representation, the register, transfers and custody each require their own analysis.
When it suits. Where the fund addresses qualified investors and seeks an institutional wealth management environment. Its limitation is that neither a Swiss authorisation nor a Swiss structure automatically opens access to investors in the European Union or the United States.
3. The European Union: the internal market
The first distinction is the previous article’s: where the token represents a unit in a fund and is a financial instrument, it falls outside MiCA’s general regime. What applies is collective investment scheme and financial markets law.
UCITS funds, under Directive 2009/65/EC, answer to harmonised requirements of investor protection, diversification, liquidity and supervision, and their regime permits units to be marketed across Member States through the mechanisms provided. Alternative investment funds, under Directive 2011/61/EU, offer more room for real estate, private equity or credit strategies, with a passport oriented principally to professional investors.
Hence a tokenised fund in Luxembourg or Ireland is attractive, but not because those States grant any licence to tokenise: what they offer is familiar structures, managers, depositaries, administrators and cross-border marketing mechanisms. The choice between them and Spain or another Member State turns on the form of the vehicle, the investor type, eligible assets, operating cost and the availability of regulated providers.
To which is added Regulation (EU) 2022/858, the pilot regime for DLT-based market infrastructures, which permits experimentation with the trading and settlement of certain tokenised financial instruments within narrow quantitative limits. It does not replace the fund’s regulation, nor does it automatically supply trading infrastructure. And what is in force should be distinguished from what is pending: the Commission put forward a proposal on 4 December 2025 to widen its scope and remove the per-instrument caps, which has not been adopted.
When it suits. Where the objective is to reach European investors or to operate cross-border within the internal market. Its difficulty is the accumulation of requirements on management, depositary, distribution and registration, which tokenisation does not reduce.
4. The table, and what the table does not resolve
| Criterion | United States | Switzerland | European Union |
|---|---|---|---|
| Natural market | US investors | Qualified investors | European investors |
| Framework | Federal securities and fund law | CISA, FinIA and DLT rules | UCITS, AIFMD, MiFID II, pilot regime |
| Advantage | Market depth | Routes for professional investors | Passport and internal market |
| Limit | Complexity and compliance cost | Cross-border access is not automatic | Accumulated operating requirements |
| Critical question | Register, intermediaries and custody | Nature of the token and of the vehicle | Register, depositary and marketing |
The table orients and does not decide, because the fund’s jurisdiction and its investors’ jurisdiction are not the same, and that difference conditions the whole structure. A US fund addressing European investors must attend to EU marketing requirements. A Swiss fund addressing US investors will meet the restrictions of federal securities law. And a European fund operating on a public chain acquires no new capacity to market its units anywhere.
5. Tax matters, but does not decide alone
Separate the taxation of the vehicle, that of its investors, withholding on the income of the underlying assets, and the consequences of distributions and transfers; then attend to effective tax residence, substance, double taxation treaties and anti-abuse rules.
There is no general answer as to which jurisdiction is more tax-efficient for a tokenised fund. A structure that is efficient in the country of establishment may be considerably less so for its investors. And the blockchain changes how rights are represented and transferred; it does not alter the tax obligations attaching to them.
6. The question that occupies us: where will the rights be enforceable?
So far we have compared regulatory regimes. What is missing is the question that rarely appears in a structuring note, and which determines what the compared rights are worth.
An investor may dispute a redemption value, claim title to units, or allege an unauthorised transfer. A custodied asset may be lost, an administrator may err, or the fund’s register and the chain may diverge. And in an international structure those disputes involve persons established in different countries: the fund in Luxembourg, the manager in Switzerland, the depositary in a third State, investors across three continents, and the chain operating on a network belonging to no jurisdiction at all.
In that setting, choosing a country of establishment resolves none of three things.
The first is the applicable law, which is not one law but several: the law governing the rights carried by the token, the law determining title to the units, the law regulating the manager’s obligations, and the law fixing the depositary’s liability. A contractual choice of law does not displace the mandatory rules applicable to each of those relationships.
The second is the dispute resolution mechanism. International arbitration fits cross-border relationships of this kind, but — and this is where the most expensive mistakes are made — the arbitration agreement must validly bind each party concerned, which is built into the contractual relationship with each of them and not achieved by cross-reference from the fund documents. The depositary is not bound by virtue of being the depositary. And the dispute must be arbitrable under the applicable law, whose mandatory limits do not disappear because the clause is well drafted.
And the third is what the decision reaches once made. An order to deliver units is performed only if someone can register that delivery. A monetary order requires a valuation date, and with a periodic net asset value and a token trading continuously those are two different figures. If the underlying asset sits in a control structure that admits an adjudicated decision, the decision arrives; if not, it is an order directed at someone with no reason to comply with it.
And here is what no comparison table shows: financial regulation in these three jurisdictions does not, by itself, guarantee that a judicial or arbitral decision can be effectively reflected in the register of units and in control over the tokenised assets. The United States, Switzerland and the European Union regulate who may manage, with what capital, under what supervision and with what disclosure. But whether there is a channel by which a decision reaches the unit and the asset does not come from the fund’s flag: it comes from the custody architecture and the contract, and it is decided at the structuring stage or never.
So the question people start with — where is it easiest to issue — is the least important of all. The one to ask first is where the investors will be, under which law, and by what route a decision will reach them if something goes wrong.
Institutional interest note: BACS (Blockchain Arbitration & Commerce Society) is a non-profit association registered in the European Union Transparency Register under number 9106897105368-14, and has established an international tribunal of arbitration, BACSIT, which administers proceedings under its own rules. This analysis is general in nature and does not constitute legal advice on any particular project or jurisdiction.
Sources: FINMA, approval of the Crypto Market Index Fund, 29 September 2021; FINMA, communication on the Limited Qualified Investor Fund, in force since 1 March 2024; JPMorgan OnChain Liquidity-Token Money Market Fund, SEC filing (JPMorgan Trust IV, 2026); Investment Company Act of 1940; Directive 2009/65/EC (UCITS); Directive 2011/61/EU (AIFMD); Regulation (EU) 2023/1114 (MiCA), article 2(4); Regulation (EU) 2022/858 and the Commission’s reform proposal of 4 December 2025.