In our previous article we argued that relationships living inside global digital infrastructures need more than the classical territorial connecting factors, and we proposed speaking of an Internet Jurisdiction: a functional legal space, not a new territory. That piece closed by pointing to arbitration as the bridge between a legal decision and on-chain enforcement.
It is time to develop that. Saying arbitration is the right route resolves nothing on its own: the practical question is what an arbitration agreement must contain in order to work when the subject matter of the dispute is a digital asset, and what it still cannot do however well it is drafted.
The problem is not the absence of a judge, but the absence of an anchor
It is worth being precise about where the difficulty lies. It is not that no court will hear a crypto-asset dispute: courts will, and increasingly do. The difficulty comes earlier. The categories by which a court decides whether a matter is properly before it — the defendant’s domicile, the place of contracting, the place where the damage occurred, the place where the asset is situated — apply awkwardly to a relationship whose participants may be pseudonymous, whose contract is a programme deployed on a network with no seat, and whose object is either nowhere in particular or everywhere at once.
The usual result is not that nobody has jurisdiction. It is the opposite: that several fora might, that none clearly does, and that the claimant discovers which one after months of preliminary litigation about jurisdiction, while the asset changes hands.
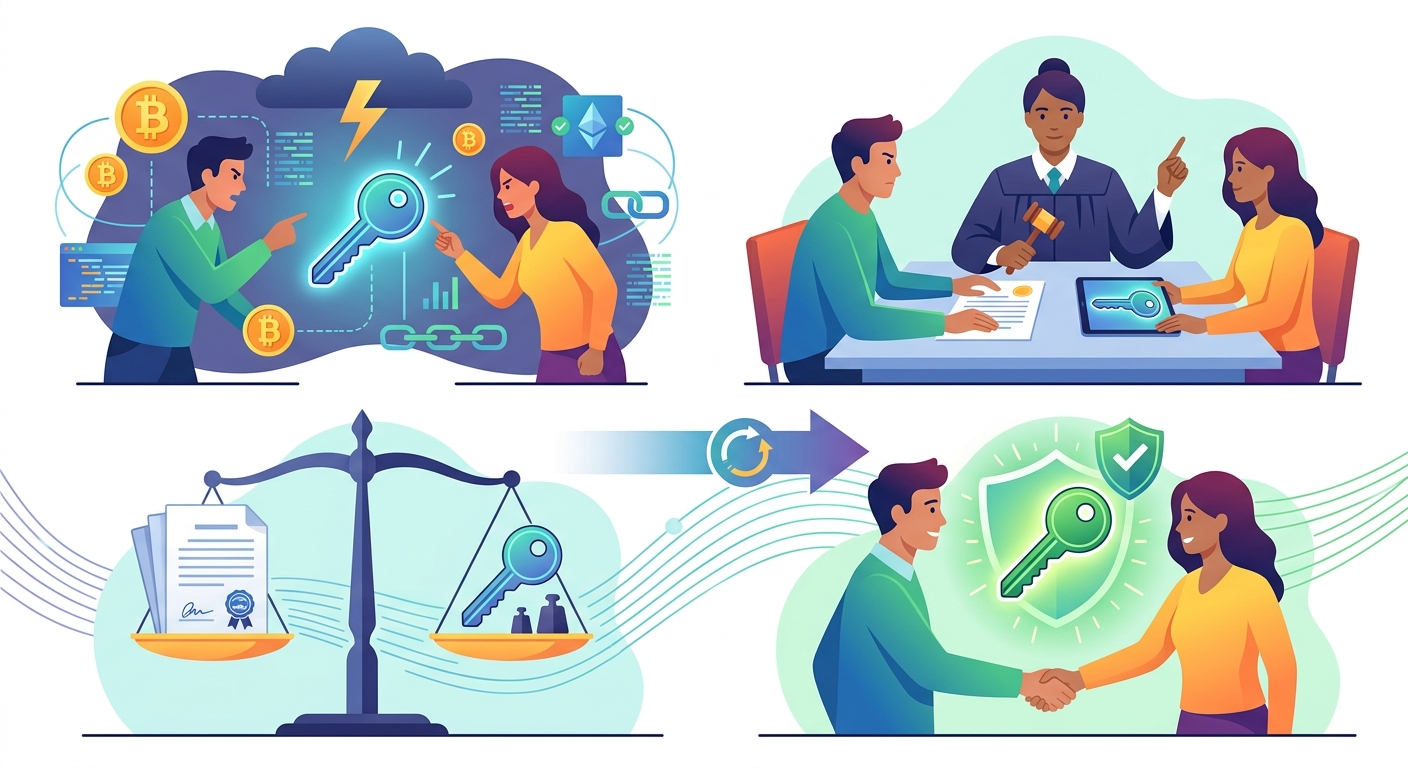
Arbitration does not resolve that conceptual difficulty. It does something more modest and more useful: it sidesteps it. Party autonomy supplies the anchor the network lacks. The parties choose the forum in advance and, with it, the seat, the law governing the procedure and the framework for recognition of the award. What in court proceedings is a preliminary battle becomes, in arbitration, a clause.
What a generic clause leaves uncovered
This is the point most often missed. Most documents in the sector — protocol terms of use, contributor agreements, offering documents, custody agreements — today carry a boilerplate arbitration clause: any dispute arising out of this agreement shall be resolved by arbitration administered by [institution] under its rules.
That clause is valid and better than nothing. But it is designed for an ordinary commercial contract, and it leaves unresolved four questions that, in a digital asset dispute, are precisely the ones that decide the case.
First: what counts as evidence, and with what weight
Proceedings over digital assets rest on material no classical set of rules contemplates: on-chain transaction records, forensic analysis reports, governance logs, snapshots of a smart contract’s state, code audit reports.
Is a block explorer extract admissible as documentary evidence? Who establishes that the address in question belongs to the respondent? What standard of authenticity applies to a report from an on-chain analytics firm?
If the clause is silent, this will be argued during the proceedings, with the cost and delay that entails.
Second: the tribunal’s technical competence
An arbitrator experienced in international contracting is one thing; an arbitrator able to read a transaction trace, or to understand why a compliance module rejected a transfer, is another.
The clause can require that at least one member of the tribunal demonstrate technical competence in the field, or provide for a tribunal-appointed expert. If it does not, the practical alternative is that both parties produce party experts and the tribunal chooses between two opposing technical accounts with no independent basis for doing so.
Third: the speed of interim measures
This is the decisive difference from ordinary litigation. A building is still where it was six months later; funds at an address can be split across dozens of destinations in an afternoon.
A useful clause provides for an emergency arbitrator, for abbreviated timetables and, above all, makes clear that applying to a state court for urgent interim relief does not waive the arbitration agreement.
That last point, apparently formal, is what allows a freezing order to reach an exchange in hours rather than weeks.
Fourth: who else is in the dispute
Almost no real digital asset dispute is bilateral. There is the issuer and the investor, but also the custodian, the valuation oracle provider, the contract developer, the issuing vehicle and sometimes the organisation that voted the decision through.
If the clause provides for neither consolidation nor the joinder of third parties bound by parallel agreements, the result is a set of separate arbitrations over the same facts, with a real risk of inconsistent outcomes.
The honest limit: what an award cannot reach
This must be said plainly, because the sector’s rhetoric tends to promise more than legal technique can deliver.
An arbitral award is an enforceable title and, under the 1958 New York Convention, is recognisable in more than one hundred and seventy States. That is a great deal. But an award operates in personam: it obliges a person to do something. It does not itself move an asset on a blockchain, does not reverse a confirmed transaction, and has no effect whatever on someone who controls a set of keys and chooses not to comply.
Put differently: effective enforcement still requires, in the final stretch, either the voluntary cooperation of the obligated party, or an identifiable intermediary subject to jurisdiction — an exchange, a custodian, an issuer with freezing capability — or the intervention of a state judge over the respondent’s ordinary assets.
Where none of the three exists, the award is legally impeccable and practically useless.
Acknowledging that limit does not weaken arbitration: it situates it. And it explains why enforcement, rather than jurisdiction, is the genuinely open problem in this field.
Where this points
This is where what we at BACS have been calling legal oracles comes in.
A data oracle brings information from the outside world into an on-chain system so that the system can execute. A legal oracle would do the same with a decision: translate the content of an award into an instruction executable by the system where the asset resides.
This is neither science fiction nor a redesign of arbitration. It requires that infrastructure be designed, from the outset, on the assumption that a legitimate external decision may need to be incorporated: an execution role tied to the outcome of arbitral proceedings, a bounded freezing capability, a restitution route contemplated in the contract itself.
What is today resolved through an order addressed to a third party could be resolved by structural provision.
In the meantime, the practical recommendation is simpler and more urgent: review the clause.
Most projects operating with digital assets today carry an arbitration agreement that would not survive the first serious dispute — not because it is invalid, but because it is generic. And the time to fix that is now, not on the day the funds are already moving.
BACS operates a Court of Arbitration specialised in digital assets and therefore has a declared institutional interest in this field. This article is for informational purposes and does not constitute legal advice.
This article continues our reflection on «Internet Jurisdiction: the next step in private international law».